Privacy Policy

Saturday, 30 April 2011

Some Thoughts on Foreign Currency Time Deposits

Image: www.businesscafeonline.com
A friend asked me this question:
What is your view of RMB time deposit offered by bank of china? The offer is found here.

My answer is: Dear Mr. A,
I had a brief look at what the offer is. I can't say I know too much about currencies and of this specific deal. And what I am about to say, might be factors that might be already obvious to you. But here goes:
You are taking on 2 main exposures by doing it. 

First, currency exposure, i.e. the fluctuation of the RMB versus your home currency (I presume you are thinking of changing SGD to RMB, but it could also be USD/RMB or some other currency pair). 

The appreciation or depreciation of a foreign currency depends on a few factors, which are affected by macro-economic policies which might be unforeseeable, and also the relative strength of the 2 economies, their interest rate differential and their inflation rate differential (this is actually Fisher's interest rate parity theorem). And of course if the current pricing is inefficient, then there are also sentiment driven factors. But let's assume the currency market is efficient (in the parlance, we'd call that the null hypothesis), which it likely is, since the currency market is one of the most liquid, if not the most liquid market in the world. 

Where any of these factors are going, and the relative strength of it versus Singapore is hard to predict, and the interaction of the factors are complex. So, you have to ask yourself whether you believe that the RMB is going to appreciate against the SGD. If it depreciates instead, it could offset the yield that you were getting from the RMB time deposit.

Disclosure: My experience in forex is limited, I have used currency swaps structured similar to forex time deposits before, as I was posted aboard for a period, and of course the usual forex transactions when travelling. I currently have no direct or derivative positions on forex but have foreign asset holdings denominated in foreign currencies and some tiny amounts of paper currencies.

Friday, 29 April 2011

Is Microsoft a Good Value Play?

Image: Microsoft
Microsoft used to be THE company everyone loves to hate (now it's the banks), complaining about its blue screens of "death" and just disliking its dominance of the PC market. 

Today, MSFT seems almost like a lost cause, having floundered for 10 years with its share price going nowhere. With its PE ratio this cheap (10.4x trailing twelve months), coupled with strong cashflows, MSFT is a monopoly priced like a sunset industry. 

With its products spanning a wide range from the X-box for the gaming crowd, to its ubiquitous Windows OS and Office suite for the business people, and consumers too, MSFT seems extremely cheap for what is among the most universal of all brands and products. And we haven't even factored how it might dominate in cloud, which is lauded as the next big thing. Is MSFT a good value-play? 

DR Horton: Buy, Hold or Sell?

If you want to play the housing recovery theme, first read the post that's just before this one.

If stocks are your favoured instrument, one place to start is to examine the major homebuilders in the USA and examine which among them is best managed and positioned to ride this potential recovery. 

Image: Dr Horton
The biggest among them is worth investigating - DR Horton (NYSE: DHI). With its operations spanning the entire continental USA, its use of land parcel options to hedge its  purchases for its land portfolio, and its decent financials, DHI is well positioned to benefit from an upturn. The land options are real options, i.e. they are not financial derivatives but ones that involve the receipt of actual plots of land and can be viewed as call options.

However, if the housing market double-dips or crashes, DHI would naturally follow the industry's downturn. So first decide if housing is going to make a comeback (which it has not yet failed to do before since we actually all need housing and not "eyeballs" or tulips), or not.

Disclosure: I have direct holdings in DHI.

I use the term direct holdings because for some companies, I might have indirect holdings for example in an indexed ETF. I do not use derivatives, though I might in future. A direct holding is a very specific investment or "bet" and stockpicking is not for those not versed in financial analysis. 

A widely diversified ETF or mutual fund might be a better instrument for those wanting to ride with the market, or even to play specific sector themes. In this case, housing sector ETFs are available, but as with all investments, you should conduct your own research to determine its suitability for your portfolio.

Thursday, 28 April 2011

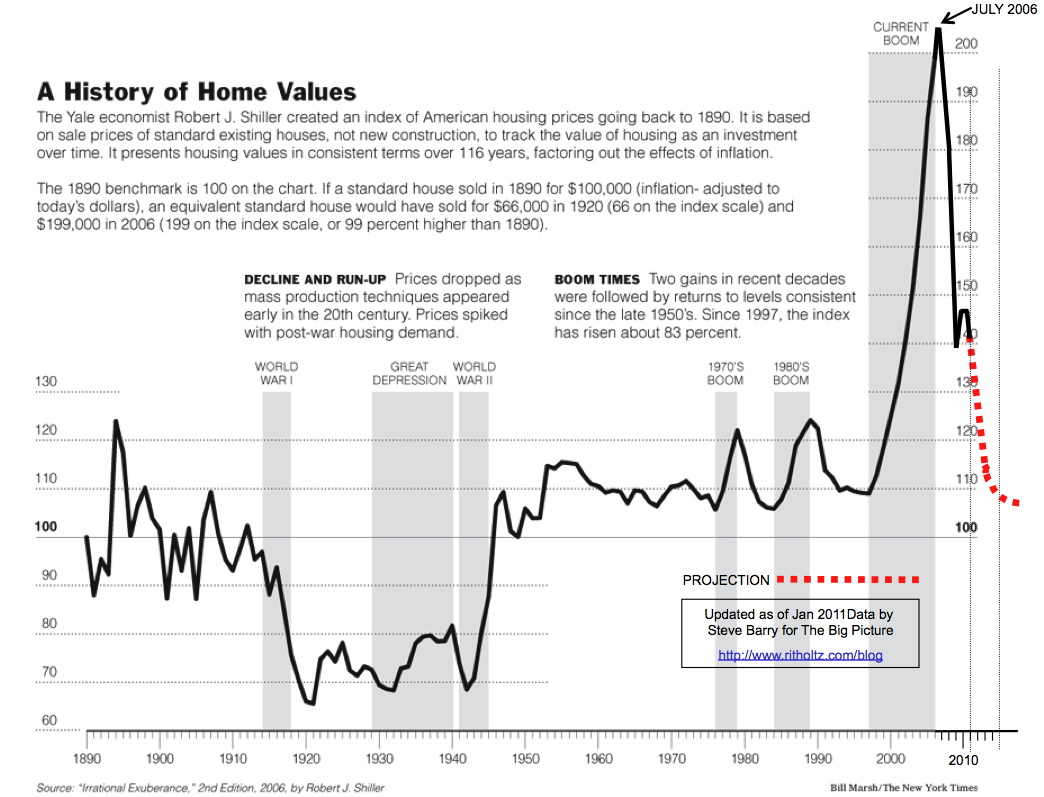
Contrarian on Housing?

For those considering a contrarian play on housing in the US market, you might do well to read this on Seekingalpha.com. It discusses whether you should use physical real estate or homebuilder stocks as your instrument and its pros and cons.  

Mean Reversion?
Source: Seekingalpha
The real difficulty of being contrarian is that while it might seem obvious as a "fantastic" opportunity on hindsight if homebuilder stocks see a strong recovery on the back of an improving housing market, there are also 1001 reasons why there might not be such a great recovery, all seemingly very logical. 

It never is easy being contrarian, which is why while everyone knows the dictum to buy low and sell high, or Warren Buffet's famous phrase, "be fearful when others are greedy and be greedy when others are fearful" seems like a truism, it is actually extremely difficult to execute.

Tuesday, 26 April 2011

IBM: Buy, Hold or Sell?

Since IBM sold off its PC business, moving away from the "commoditised" consumer computing sector into the more high end consulting and analytics business to serve the enterprise customer, its growth rate is nothing short of startling.

IBM might not be as hot as Google or Apple, but with a CAGR since 2006 greater than 17% and pre-tax income margins at 19.7% in 2010, IBM's modest PER of 14.6x might seem like a bargain.

Here's what they have been up to recently:

After Deep Blue vs Kasparov, IBM's engineers have been looking for the next challenge and found it in this supercomputing powering natural language processing Jeopardy showdown. But it isn't all fun and games at work. They believe that this technology can help businesses work better and they want to create a "smarter planet". They also have an ambitious plan to execute with their 5 year roadmap (to 2015). With a track record to boot, is IBM a growth company priced like a mature one?

Disclosure: At the time of post, I did not have open positions in IBM. Since then, I now have direct holdings in IBM.

Sunday, 17 April 2011

Preferred Shares: The Worst of Both Worlds?

Is this worth the paper 
it's printed on?
Image: www.greekshares.com
In light of a slew of offerings for preferred or preference shares on the Singapore bourse, and after a few enquiries from friends, I thought it might be good to touch on what this class of securities represent and how a prospective investor should look at it. 
 
I have heard several people compare preferreds to bonds or to even fixed deposits, but that is a gravely mistaken way of looking at it, since the risks are higher (in some cases, much higher).
Disclosure: I do not hold any preferred stock of any firm.

Thursday, 14 April 2011

Walmart: Buy, Hold or Sell?


Until recently, Walmart's dominance on the supermarket retail space was practically unchallenged. With the advent of the financial crisis, bargain shops have begun to encroach on WMT's territory, and online retailers like Amazon also has similar ambitions. However, WMT still is a gorilla in retail, and its business model of providing cheap groceries and other household items, with "Low Prices. Everyday. On Everything"  essentially sums up why its market share would be hard to erode. WMT is still cheap due to the headwinds from a recovering US economy but the defensive nature of the company and its leadership in retail  positions it well when the economy stabilises, best seen when unemployment sustains its downward trend.

But as with all investment analyses, the question is, what is the right price?   As usual, click read more, to, read more!

On a seperate note, I have discontinued placing the spreadsheets of my calculations online. I typically only keep 1 version of these sheets and update them or use them in scenario testing. Hence the data might have changed since the original time of analysis. If you do wish to obtain my calculations, please email me and we can also discuss the analysis offline.

Disclosure: I have direct holdings in WMT, but not in AMZN.

Medtronic: Buy Hold or Sell?

Medtronic is the leading maker of medical devices, with its string of innovative products that can be powering a failed heart, or valves, and basically while I know little about medicine, the company does seem to have a good set of financial metrics worth examining further.

Dreamworks Animation: Love the Movies, Not So Hot on the Stock


Shrek - who has not seen it, in fact, all 4 increasingly bad installations of it. But love it or hate it, Dreamworks Animation has created a huge green monster franchise from it. With its string of other box office successes such as How to Train A Dragon and Megamind, DWA's 3D animation legacy looks sealed in concrete, and a viable competitor among the other movie studios. Great movies! But does it make for a great investment?


Disclosure: I have no holdings in DWA.